Hero Homes

Author name: Admin

Walk Through Your Dream Home: A 10-Minute Visualisation Exercise
Uncategorized

Walk Through Your Dream Home: A 10-Minute Visualisation Exercise

Most of us describe our dream home as a list: three bedrooms, a balcony, and a modular kitchen. But a list doesn’t tell you how a home feels on an ordinary Tuesday. This exercise does. You’ll walk through one full day in your ideal home, from waking up to falling asleep, and notice what you need. It takes 10 minutes, and all you need is a pen and paper (or your phone’s notes app). How it works: Read each step, pause, and answer the prompts in your head. Jot down just a word or two for anything that stands out. There are no wrong answers, so don’t overthink it. Minute 0-1: Settle In Close your eyes for a moment and take three slow breaths. Imagine standing outside your dream home. Minutes 1-3: Waking Up It’s morning, and you’re waking up in your bedroom. Jot down: the one detail that makes this wake-up feel perfect. Minutes 3-4: The Morning Routine You head to the bathroom, then the kitchen. Jot down: what your morning space needs (light, storage, a seat, a view). Minutes 4-6: Your Daytime Now imagine the middle of your day. Jot down: your ideal location features and any work-from-home needs. Minutes 6-8: The Evening You’re back home, and the day is winding down. Jot down: the spaces you’d actually use every day, not just the ones that look good. Minutes 8-9: Night It’s time to wind down. Jot down: what you need for a peaceful night (silence, privacy, ventilation). Minutes 9-10: Capture It Open your eyes and look at what you’ve written. Circle the 5 details that mattered most to you, especially anything that came up more than once. Then complete this sentence: “My ideal home must have ____, ____, and ____.” What to Do Next You now have something more useful than a generic wish list: a short, personal list of priorities based on how you actually want to live. Use it to: Do the exercise again in a few weeks. If the same details keep coming up, those are your real priorities. Tell us in the comments: what was the one detail that surprised you most?

Uncategorized

Small Home, Big Happiness: 7 Reasons Compact Living Beats a Large House

For years, owning a large house has been considered a sign of success. Bigger living rooms, extra bedrooms, spacious balconies, and impressive interiors often make their way onto the dream-home checklist. But homeownership is changing. Today, many homebuyers are looking beyond square footage. They want a home that fits their lifestyle, supports their financial goals, and makes everyday living easier. This is where compact homes are gaining attention. A thoughtfully designed 2 BHK apartment or a well-planned compact home can offer everything a modern household needs without the additional financial and maintenance responsibilities of a much larger property. Of course, a smaller home is not automatically a better home. The difference lies in how efficiently the available space is designed and whether it suits the people living in it. So, is buying a compact home a smarter decision than investing in a large house? Here are seven reasons why compact living may offer more value, comfort and happiness than you might expect. 1. Lower Purchase Costs Leave More Room in Your Budget One of the biggest advantages of choosing a compact home is its relatively lower purchase price. In cities such as Delhi, Gurugram, Noida, Bengaluru and Pune, property prices can vary significantly depending on the location, developer, amenities and configuration. Within the same project or locality, a smaller apartment may cost considerably less than a larger one. The financial benefit goes beyond the initial purchase. A lower property price can mean: For example: Suppose two properties have different purchase prices: Assuming a 20% down payment and a 20-year home loan at an illustrative 8.5% annual interest rate: Particulars Compact Home Larger Home Property price ₹55 lakh ₹85 lakh Down payment ₹11 lakh ₹17 lakh Loan amount ₹44 lakh ₹68 lakh Approx. monthly EMI ₹38,200 ₹59,000 These are illustrative calculations, not current loan quotations. Actual EMIs depend on the lender, interest rate, tenure and other charges. The difference in monthly EMI is approximately ₹20,800. That money could contribute towards investments, children’s education, travel, retirement savings or an emergency fund. The real benefit of a compact home is not simply spending less. It is having more financial freedom after buying it. 2. Lower Maintenance Means Less Everyday Stress A large house often comes with more responsibilities. More rooms mean more surfaces to clean, more lights and appliances to maintain, and potentially higher repair and upkeep expenses. For working professionals, young couples and smaller families, managing all these responsibilities can become time-consuming. Compact homes make everyday maintenance easier when they are designed efficiently. Consider the practical differences: Maintenance costs also depend on the property’s construction quality, building facilities, society charges and usage patterns. A compact apartment in a poorly maintained building can still be expensive to maintain. Before purchasing, check the monthly maintenance charges, sinking fund contributions, lift facilities, water arrangements, and the condition of common areas. A home should make daily life comfortable, not create another full-time responsibility. 3. Every Corner Can Have a Purpose. A common misconception is that smaller homes always feel crowded. In reality, poor space planning is often a bigger problem than limited square footage. A compact home with intelligent design can feel more functional than a larger property with poorly utilised rooms. For example, a well-planned compact apartment can include: The idea is to make every corner useful without filling the home with unnecessary furniture. When evaluating a compact property, pay attention to the actual carpet area rather than relying only on the advertised super built-up area. Check whether the living room accommodates your furniture, whether bedrooms have sufficient wardrobe space, and whether the kitchen provides practical storage. A thoughtfully designed home can make even limited space feel welcoming. 4. More Money for Experiences, Not Just Property Buying a house is a major financial milestone, but it should not consume every other financial goal. Some homebuyers stretch their budgets to purchase larger properties because they believe more space automatically means a better lifestyle. However, a home is only one part of life. People also want to travel, spend time with family, pursue hobbies, enjoy weekends and build financial security. Choosing a reasonably priced compact home may leave more money available for these experiences. For instance, instead of spending heavily on additional rooms that remain unused, a family could allocate its savings towards: The goal is not to compromise on comfort. It is to avoid paying for space that does not contribute meaningfully to your lifestyle. A home should support the life you want to live, rather than becoming the only thing you spend money on. 5. Easier to Keep Organised and Clutter-Free A large home provides more storage opportunities, but it can also encourage unnecessary accumulation. Extra cupboards, unused bedrooms and additional storage areas sometimes become places where unwanted belongings are kept for years. Compact living encourages people to think more carefully about what they purchase and retain. This does not mean giving up everything or adopting an extreme minimalist lifestyle. It simply means being more intentional about the things you bring into your home. A few practical habits can make a significant difference: Research published in the Journal of Environmental Psychology in 2021 examined the relationship between household clutter and wellbeing among 1,111 adults. The researchers found that subjective clutter and people’s psychological connection with their homes were important predictors of wellbeing. This suggests that how comfortable and organised a home feels can matter just as much as its physical dimensions. A clean, organised living environment can make everyday routines more enjoyable. 6. Potentially Lower Energy Consumption Another practical benefit of compact living is the possibility of reducing household energy requirements. A smaller space generally requires less area to illuminate and may need less cooling, particularly when the home has good ventilation, suitable window placement and effective insulation. For Indian households, where air conditioning, fans, lighting and other electrical appliances contribute to monthly electricity bills, this can make a noticeable difference. However, actual savings depend on several factors: A compact apartment with poor ventilation

Hero Homes Sector MU Price Update
Uncategorized

Hero Homes Sector MU Price Update: What Buyers Should Know

The residential property market in Greater Noida continues to attract buyers looking for modern apartments, planned communities, and long-term homeownership opportunities. One of the projects attracting attention is Hero Homes Sector MU, now known as Leafsong Retreat following its UP RERA registration. The project is listed under registration number UPRERAPRJ414014/10/2026. The latest pricing schedule shared for the project introduces three stages, beginning with the pre-launch price and moving to the allotment day rate before the subsequent launch price takes effect. For prospective buyers, the key question is not simply whether the price will increase, but how that change affects their budget and whether the property suits their needs. Leaf Song Retreat Price List for October 2026 The announced pricing schedule outlines the following rates per square foot. Pricing stage Price per sq. ft. Validity Pre-launch offer ₹10,999* Until October 25, 2026 Allotment Day price ₹11,499* From October 26, 2026 Subsequent launch price ₹13,000 As announced for the launch stage These prices are based on the pricing details provided for this article. Buyers should obtain written confirmation of the applicable rate, area calculation, and offer conditions from the developer or authorized sales team. The pre-launch price is available until October 25, while the next rate begins on October 26, designated as Allotment Day. The subsequent launch price is ₹13,000 per sq. ft. Therefore, buyers considering the project should review the current price sheet and payment terms before making a booking decision. How Much Can Buyers Save at the Pre-Launch Price? The difference between the three quoted rates is worth examining before deciding when to buy. For example, on a hypothetical area of 1,000 sq. ft., the basic price calculation would be as follows. Pricing stage Basic price for 1,000 sq. ft. ₹10,999 per sq. ft. ₹1,09,99,000 ₹11,499 per sq. ft. ₹1,14,99,000 ₹13,000 per sq. ft. ₹1,30,00,000 At the quoted rates, the difference between the pre-launch price and the subsequent launch price would be ₹20.01 lakh for 1,000 sq. ft. However, this is an illustrative calculation, not a quotation for a specific apartment. The actual amount payable depends on the applicable saleable area, apartment configuration, additional charges, and the final price sheet. Buyers should also confirm whether the advertised per-square-foot rate applies to the entire unit area or another defined area measure. What Is Leafsong Retreat in Sector MU, Greater Noida? Leafsong Retreat is a residential development by Hero Realty Private Limited under the Hero Homes brand. The project is located in Sector MU, Greater Noida, and is registered with the Uttar Pradesh Real Estate Regulatory Authority under registration number UPRERAPRJ414014/10/2026. For buyers searching online, it is useful to recognize both names, Hero Homes Sector MU and Leafsong Retreat. This helps when comparing project information, searching for floor plans, or requesting the latest price list. Nevertheless, a project name and registration number alone should not determine a purchase decision. Buyers should examine the approved plans, apartment specifications, declared completion timeline, and contractual obligations before paying a booking amount. Leafsong Retreat is a residential development by Hero Realty Private Limited under the Hero Homes brand. The project is located in Sector MU, Greater Noida, and is registered with the Uttar Pradesh Real Estate Regulatory Authority under registration number UPRERAPRJ414014/10/2026. For buyers searching online, it is useful to recognize both names, Hero Homes Sector MU and Leafsong Retreat. This helps when comparing project information, searching for floor plans, or requesting the latest price list. Nevertheless, a project name and registration number alone should not determine a purchase decision. Buyers should examine the approved plans, apartment specifications, declared completion timeline, and contractual obligations before paying a booking amount. Should You Book Before October 26? The pre-launch price may appeal to buyers who have already evaluated the project and are comfortable with the financial commitment. However, a lower advertised rate does not automatically make a property the right choice. Before booking Leafsong Retreat, consider the following factors. 1. Verify the final price. Request a written cost sheet that specifies the applicable rate, apartment area, floor-related charges, parking charges, taxes, and other applicable costs. 2. Review the RERA documents. Search for the project on the official UP RERA website and verify the registration number, promoter details, approved plans, and declared completion date. 3. Compare apartment configurations. Examine the available layouts, usable space, ventilation, orientation, and floor options. A difference in the quoted rate may not be the only factor affecting overall value. 4. Understand the payment schedule. Confirm the booking amount, installment dates, cancellation terms, and any conditions attached to the pre-launch offer. 5. Assess the location for your needs. Consider your workplace commute, nearby schools, healthcare facilities, daily shopping requirements, and available transport links. Visit the location to evaluate the surroundings rather than relying solely on marketing material. These checks can help buyers distinguish a genuinely suitable home from an offer that appears attractive mainly because of its price deadline.
Dussehra: 5 Resolutions for Aspiring Homebuyers
Uncategorized

Dussehra: 5 Resolutions for Aspiring Homebuyers

Dussehra, also known as Vijayadashami, is a festival that celebrates the victory of good over evil and marks the triumph of determination, courage, and righteousness. It is also an ideal time to reflect on personal goals, embrace new beginnings, and take meaningful steps towards a brighter future. For many families, owning a home is one of life’s biggest aspirations. A home represents security, stability, financial growth, and a place where countless memories are created. If buying a home is on your wish list, this Dussehra can be the perfect occasion to turn that dream into a well-planned reality. Whether you are a first-time homebuyer or planning to upgrade to a bigger space, here are five resolutions for aspiring homebuyers this Dussehra to help you move closer to owning your dream home. 1. Resolve to Set a Realistic Homebuying Budget Every successful homebuying journey begins with a clear financial plan. Before exploring properties, take time to assess your income, savings, monthly expenses, existing financial commitments, and future goals. Setting a realistic budget helps you identify properties that match your financial capacity and prevents unnecessary financial stress later. What you can do this Dussehra: Remember, the right home is not just one you love; it is one you can afford comfortably. A well-planned budget lays the foundation for a confident and stress-free homebuying experience. 2. Resolve to Improve Your Credit Score and Financial Health If you are planning to finance your dream home with a home loan, your credit score and overall financial profile deserve special attention. Lenders generally consider your credit history, repayment capacity, income stability, and existing liabilities when evaluating a home loan application. A healthy credit profile can improve your chances of loan approval and may help you access more favourable loan terms, depending on the lender’s policies. What you can do this Dussehra: Think of this resolution as clearing financial obstacles on your path to homeownership. Better financial discipline today can make your homebuying journey smoother tomorrow. 3. Resolve to Research Locations and Choose the Right Property Choosing a home involves much more than selecting an attractive apartment or an independent house. The location, connectivity, neighbourhood, infrastructure, and access to everyday conveniences can significantly influence your quality of life and the property’s long-term value. Before finalising a property, consider your daily commute, proximity to schools and healthcare facilities, public transport, shopping areas, and future infrastructure developments. What you can do this Dussehra: Most importantly, conduct proper legal due diligence. Verify the property’s title, applicable approvals, agreement terms, and relevant RERA registration details where applicable. For under-construction properties, review the project’s status and possession commitments carefully. The right property should meet your present needs while supporting your long-term plans. 4. Resolve to Start Planning Early Instead of Waiting for the Perfect Time Many aspiring homebuyers postpone their plans while waiting for property prices to fall, interest rates to become more favorable, or the perfect opportunity to appear. While market conditions matter, waiting indefinitely can also delay an important life goal. Instead of trying to predict the property market perfectly, focus on what you can control: your savings, financial readiness, research, and understanding of available options. What you can do this Dussehra: Starting early does not mean rushing into a purchase. It means preparing in advance so you can make an informed decision when the right property fits your needs and budget. This Dussehra, resolve to replace uncertainty with preparation and take one practical step towards your homeownership goal. 5. Resolve to Make a Long-Term Investment in Your Future Buying a home is often one of the most significant financial decisions a person makes. Beyond providing a place to live, homeownership can offer stability, a sense of belonging, and the opportunity to build long-term wealth. However, property values can fluctuate, and a home should not be purchased solely on the assumption of guaranteed appreciation. Your decision should reflect your lifestyle, financial goals, family needs, and expected length of ownership. What you can do this Dussehra: A thoughtfully chosen home can become more than a property purchase. It can be the foundation for your family’s future, a space for celebrations, and a place to create lasting memories. This Dussehra, Take the First Step Towards Your Dream Home Dussehra reminds us that meaningful victories begin with determination and the courage to overcome obstacles. For aspiring homebuyers, the journey towards homeownership follows a similar principle: clear goals, careful planning, and consistent action can make a significant difference. By setting a realistic budget, improving your credit profile, researching the right location, planning ahead, and thinking long term, you can approach your homebuying journey with greater confidence. You do not have to accomplish everything at once. Start with one resolution, take one practical step, and gradually work towards your goal. This Dussehra, let the victory be your first step towards a place you can proudly call home. May this festive season bring prosperity, happiness, and new beginnings for you and your family. Happy Dussehra!

Rent vs. Buy The Honest Emotional and Financial Answer
Uncategorized

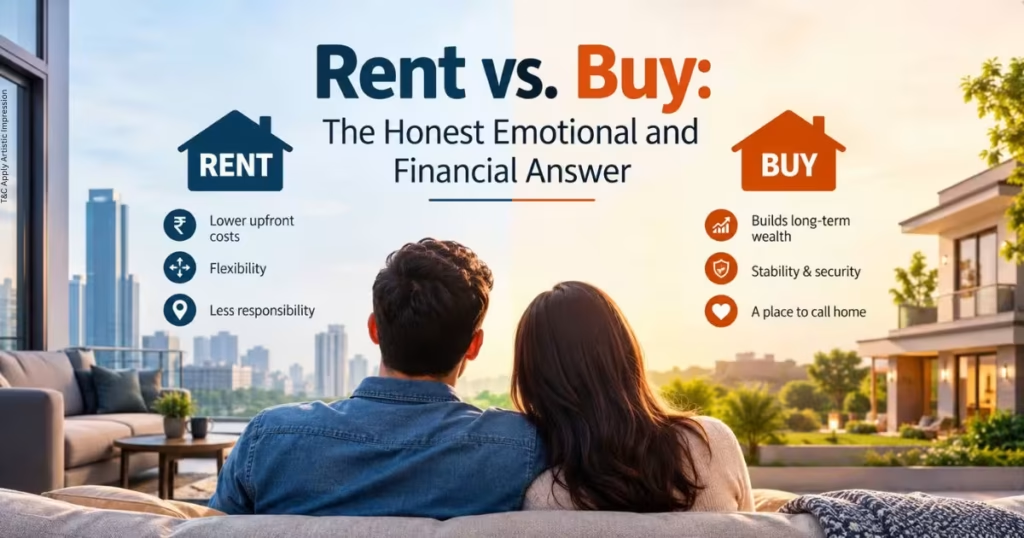
Rent vs. Buy: The Honest Emotional and Financial Answer

The decision between renting and buying a home is rarely as simple as comparing monthly rent with an EMI. A home is both a financial commitment and an emotional milestone. Renting can offer flexibility, lower upfront costs, and freedom from many ownership responsibilities, while buying can provide stability, long-term wealth creation, and the feeling of having a place that truly belongs to us. The right decision depends on our income, financial goals, lifestyle, family requirements, location preferences, and how long we expect to stay in one place. Instead of treating rent versus buy as a universal mathematical equation, we need to look at the complete picture. Rent vs. Buy: What Does Each Choice Really Mean? When we rent a home, we essentially pay for the right to use a property without taking ownership of it. Our monthly payment provides accommodation, but it does not create an ownership stake in the property. When we buy a home, our monthly housing payment contributes toward an asset. However, ownership also brings additional expenses such as the down payment, registration costs, maintenance, property taxes, insurance, and other associated charges. This makes the rent vs. buy decision more complicated than simply asking which monthly payment is cheaper. Rent may make more sense when flexibility and liquidity are priorities. Buying may become more attractive when stability, ownership, and long-term financial security matter more. The Financial Reality of Renting Renting generally requires less money upfront. Instead of arranging a substantial down payment and paying property-related transaction costs, we usually need a security deposit and the first rental payment. This can leave more money available for: Renting can also make sense for people whose careers require frequent relocation. If we are likely to change cities within a few years, buying and selling a property repeatedly may involve substantial transaction costs and inconvenience. However, there is one important financial consideration: rent does not create ownership. After years of paying rent, we still do not own the property. The landlord retains the underlying asset and benefits from any long-term appreciation. That does not make renting financially wrong. It simply means that the money we save by renting should ideally be allocated thoughtfully toward other investments and financial goals. The Financial Reality of Buying a Home Buying a home requires greater financial preparation. The initial cost may include a down payment, registration and stamp duty charges, brokerage where applicable, moving expenses, interiors, and other purchase-related costs. Homeownership also creates ongoing expenses. However, part of our housing payment can contribute toward building equity in the property. Over time, we may also benefit from property appreciation, depending on the location, infrastructure development, demand, supply, and broader real estate market conditions. For families planning to remain in the same location for many years, buying can therefore become more attractive. The important point is that a home should not be purchased simply because property prices may rise. We should first determine whether the purchase is affordable and suitable for our long-term needs. Rent vs. Buy: The Emotional Side We Often Ignore Financial calculations matter, but a home is not just an asset on a balance sheet. For many families, buying a home represents stability, independence, security, and a sense of achievement. There is an emotional difference between living in a house and owning one. When we own a property, we can make decisions about interiors, renovations, furniture, layouts, and other aspects of the living environment without being dependent on a landlord’s approval, subject to applicable rules and regulations. For growing families, ownership can also provide a stronger sense of permanence. Children can grow up in the same neighbourhood, develop friendships, attend nearby schools, and build familiarity with the community. That emotional value may not appear in a spreadsheet, but it can still be important when evaluating the decision. When Renting May Be the Better Choice Renting can be a sensible decision when our circumstances are changing. We may prefer renting if: A particularly important consideration is financial flexibility. A home should not consume so much of our income that we struggle to manage emergencies, investments, education expenses, or other essential commitments. When Buying May Make More Sense Buying may become more appropriate when we have predictable income, sufficient savings, and a clear intention to stay in a location for the long term. Homeownership can be particularly appealing when: The longer we expect to stay in a property, the more important the long-term economics of ownership can become. EMI vs. Rent: Why the Comparison Is Incomplete One of the most common mistakes in the rent vs. buy calculation is comparing rent directly with EMI. For example, if monthly rent is ₹30,000 and a potential home loan EMI is ₹45,000, it may appear that renting is automatically better. But this comparison does not account for the fact that an EMI contributes toward financing an owned asset. At the same time, it would also be incorrect to assume that every rupee paid through an EMI becomes our wealth. Home loans include interest, and homeowners also have other expenses. A better comparison considers: Rent + investment of available savings versus EMI + ownership costs + potential property appreciation + accumulated home equity This broader approach provides a much more realistic picture. The Down Payment Opportunity Cost The down payment deserves special attention. Suppose we use a significant portion of our savings to purchase a property. That money is no longer available for other investments or financial opportunities. This is known as the opportunity cost of capital. Therefore, when evaluating a home purchase, we should not only ask: Can we afford the EMI? We should also ask: Can we afford the down payment without damaging our overall financial stability? A financially comfortable home purchase should leave room for emergencies and other long-term goals. How Long Should We Plan to Stay? The expected duration of ownership is one of the most useful factors in the rent-versus-buy decision. If we may move after a short period, purchasing can expose us to

Is This the Right Time to Buy a Home? 7 Powerful Reasons
Uncategorized

Is This the Right Time to Buy a Home? Overcoming “Wait and Watch” with 7 Powerful Reasons to Act Smart

Buying a home is one of the biggest financial decisions most people make. So, naturally, buyers want to get the timing right. The common question is simple: Is this the right time to buy a home? Many prospective homeowners keep waiting for the “perfect” combination of lower property prices, cheaper home loans, better offers, and stronger market conditions. They monitor property portals, read market updates, and speak to friends. Yet, after months of research, they often find themselves exactly where they started—still waiting. This is the classic “wait and watch” approach. There’s nothing wrong with being careful. In fact, careful research is essential before buying property. The problem begins when research turns into indefinite postponement. The reality is that nobody can consistently predict the exact month when property prices will be at their lowest or when home-loan rates will be at their most attractive. Real estate decisions involve multiple factors, including location, demand, infrastructure, construction quality, financing, personal income, and long-term plans. Therefore, the better question isn’t simply, “Will prices fall?” It is: “Am I financially and personally ready to buy a home that meets my needs at a price I can comfortably afford?” That change in perspective can make the decision much clearer. For Indian homebuyers, affordability, job stability, location, connectivity, developer credibility, project approvals, and long-term usability should generally carry more weight than trying to predict a short-term market movement. This article explores 7 powerful reasons to move beyond the wait-and-watch mindset, while also explaining when waiting can actually be the smarter decision. Why Do Homebuyers Keep Waiting? Before deciding whether now is the right time to buy a home, it helps to understand why buyers hesitate. The first reason is fear of overpaying. Nobody wants to purchase a property today and discover that a similar property costs less six months later. The second is uncertainty about interest rates. Buyers taking a home loan naturally worry that a change in lending rates could increase their EMI burden. The third is market speculation. Headlines about property prices, economic growth, and infrastructure projects can make buyers believe that a major change is just around the corner. Then there is the simple human tendency to wait for certainty. Unfortunately, certainty rarely arrives in real estate. A buyer might wait for prices to fall, but prices could remain stable. Alternatively, the buyer may find that a preferred location becomes more expensive because infrastructure improves or demand increases. The same applies to inventory. A particular apartment configuration, floor, view, or location within a project may not remain available indefinitely. So, waiting has a cost too. The objective shouldn’t be to eliminate every uncertainty. Instead, buyers should reduce avoidable risks and make decisions based on facts they can reasonably evaluate. Is There Really a Perfect Time to Buy a Home? There can be good times to buy, but there is rarely a universally perfect time. The best purchase opportunity differs from person to person. For example, a salaried professional with stable income, adequate savings, and a long-term plan to stay in one city may be in a stronger buying position than someone whose employment situation is uncertain—even if both are looking at the same property. Similarly, a buyer with a comfortable down payment may have more flexibility than someone who would need to borrow almost the entire purchase amount. This is why personal financial readiness often matters more than trying to perfectly time the real estate cycle. A property purchase is also a long-term commitment. If you’re buying a home to live in for 8, 10, or 15 years, a small short-term price movement may matter less than the property’s suitability over the entire ownership period. Consider these factors: If most answers are yes, continuing to wait purely because you’re hoping for a “perfect” market may not necessarily improve the decision. 7 Powerful Reasons to Consider Buying a Home 1. Your Financial Readiness Matters More Than Market Predictions One of the strongest indicators of whether it’s the right time to buy a home is your own financial position. Suppose you’ve built a healthy emergency fund, have stable income, and can comfortably arrange the required down payment. You have also calculated the EMI and other ownership costs without stretching your monthly budget. In that situation, your personal circumstances may be more relevant than trying to predict the next movement in property prices. Before purchasing, create a realistic homebuying budget. Your calculation should include: Expense What to Consider Down payment Amount you can arrange without exhausting savings Home loan EMI Monthly repayment capacity Registration Applicable registration and documentation costs Stamp duty Applicable state charges Maintenance Recurring society/property expenses Interiors Furniture, appliances and fit-outs Emergency fund Money that should remain untouched Insurance Home and loan-related protection where applicable Don’t make the mistake of using every rupee you have for the down payment. A home should provide financial stability, not create constant financial stress. A sensible rule is to test your budget under different scenarios. What happens if your expenses increase? What if your income temporarily falls? What if the property needs additional interior work? If the purchase still looks manageable, you’re approaching the decision responsibly. The RBI has also issued guidance concerning changes in interest rates for equated-installment personal loans, including home loans, and the options available to borrowers when rates reset. Reserve Bank of India For official information, buyers can refer to the Reserve Bank of India’s borrower FAQ. The takeaway is straightforward: buy when the numbers work for you—not simply because someone says the market is rising or falling. 2. Property Price Is Only One Part of the Equation. When buyers compare properties, they often focus almost entirely on the quoted price. That’s understandable, but incomplete. A ₹70 lakh property isn’t necessarily cheaper than an ₹75 lakh property if the first property requires substantial renovation, has higher recurring costs or is located much farther from your workplace and essential services. The real cost of homeownership includes more than the purchase price. Consider: This is

Why Owning a Home Feels Like a Milestone and Not Just an Asset
Uncategorized

Why Owning a Home Feels Like a Milestone and Not Just an Asset

Buying a home is more than a financial decision. It often represents stability, growth, and personal achievement. For many people, owning a home marks an important chapter in life. It reflects years of planning, saving, and making thoughtful choices. Unlike many investments, a home becomes part of everyday life. It holds memories, celebrations, challenges, and countless personal moments. A Home Represents Personal Achievement Owning a home often begins with a simple dream. However, turning that dream into reality requires patience and financial discipline. First, buyers usually plan their finances carefully. They consider savings, income, loans, and future expenses. Eventually, receiving the keys creates a powerful sense of accomplishment. It represents the result of years of effort. Therefore, homeownership often feels deeply personal. It becomes a visible reminder of progress and determination. Financial Security Through Homeownership A property can also provide long-term financial value. Unlike temporary expenses, homeownership can build an enduring financial foundation. Furthermore, property values may appreciate over time. Market conditions, location, infrastructure, and demand can influence future value. However, homeowners also gain greater control over their living situation. They can plan their finances without depending entirely on changing rental costs. As a result, owning property can support both lifestyle goals and financial planning. A Place to Build Lasting Memories A house becomes meaningful through the experiences created inside it. Family dinners, festivals, birthdays, and quiet evenings all add emotional value. Moreover, homeowners can personalize their space according to their lifestyle. They can choose designs, interiors, furniture, and features that reflect their preferences. Over time, these choices transform a property into a personal environment. Consequently, the home becomes much more than walls and rooms. It becomes a place connected to important memories and milestones. Freedom to Create Your Ideal Space Renting a home can provide flexibility. However, ownership often provides greater freedom for customization. Homeowners can renovate rooms, upgrade interiors, or create functional spaces. They can also make improvements based on changing family requirements. For example, a growing family may need an additional study or children’s room. Similarly, professionals may prefer a dedicated workspace. Thus, homeownership allows people to shape their surroundings around their evolving needs. A Stronger Sense of Stability A permanent home can provide emotional and practical stability. This feeling becomes especially important for families planning their future. Children can grow within a familiar environment. Families can also establish routines without worrying about frequent relocations. Additionally, owning a home can create a stronger connection with the surrounding community. Neighbors, schools, parks, and local facilities become part of everyday life. Therefore, a home can provide stability that extends beyond the property itself. Homeownership Can Reflect Future Planning Buying a home usually involves thinking beyond the present. Buyers consider career plans, family needs, lifestyle preferences, and financial goals. Consequently, purchasing property often encourages long-term financial discipline. Homeowners may become more focused on budgeting and managing future expenses. Moreover, a well-chosen property can support changing needs over several years. Location and connectivity can also influence its long-term usefulness. This makes homeownership an important part of broader life planning. The Emotional Value Goes Beyond Money A property’s market value can be measured through numbers. Its emotional value cannot be measured so easily. For many homeowners, their first property represents independence. It can also symbolize confidence, responsibility, and personal growth. Every room may eventually carry a story. Every improvement may represent another stage of life. Therefore, the true value of a home often extends beyond its financial worth. A Milestone Worth Celebrating Owning a home combines financial commitment with personal aspiration. It represents the journey from planning to achievement. Of course, property remains an important financial asset. Yet its significance goes much deeper for many homeowners. A home provides space, stability, freedom, and memories. More importantly, it can represent the life someone worked hard to build. That is why receiving the keys to a home often feels like a milestone rather than simply acquiring an asset.

Scroll to Top